What an Amazon FBA Business Is Worth: How Buyers Value It and What to Fix First
A buyer pays a multiple of the profit that would survive the sale. How that profit is worked out, what brokers report the multiple to be this year and why it fell, the six things that move a business from the bottom of the range to the top, and the year of preparation a good price takes.

Loading Article banner
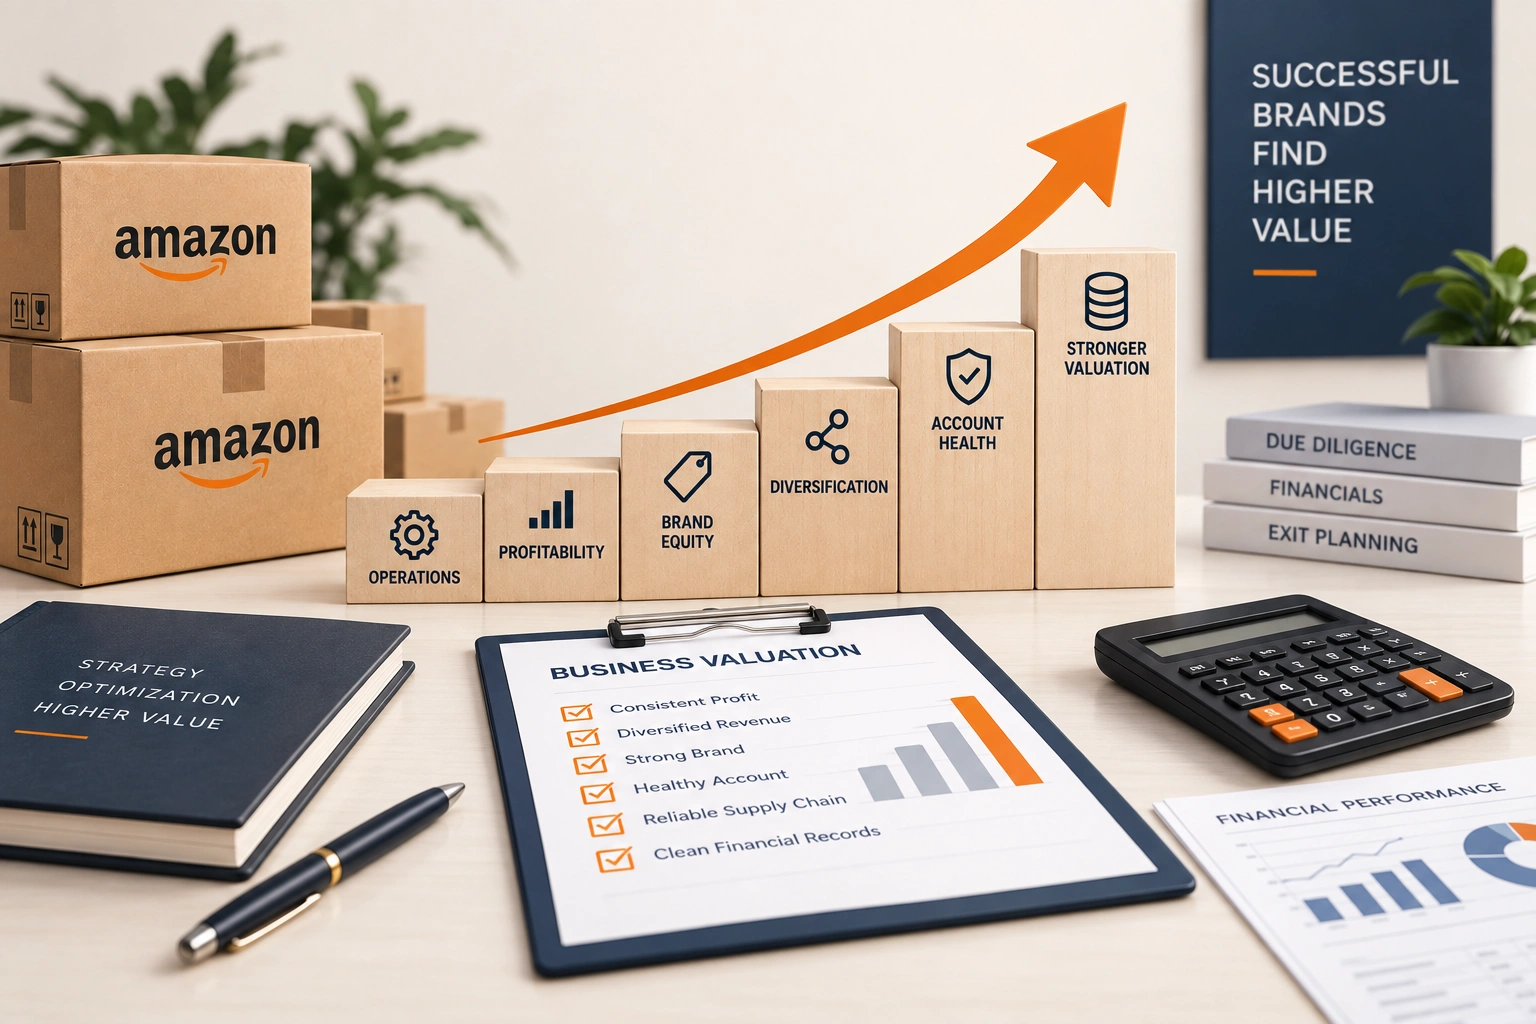
An Amazon business is sold on one number: the profit a new owner could expect to keep, multiplied by what buyers are paying this year for profit of that kind. Everything else in a sale, the diligence, the transfer, the negotiation, is an argument about those two figures. A seller who knows how each is worked out, a year before selling, ends up with a different price from one who learns at the offer.
This is how buyers work the two figures out, what brokers report the multiple to be in 2026, why it is lower than it was, and the six things that decide where in the range a particular business lands.
The profit a buyer counts
Buyers of smaller businesses use seller's discretionary earnings: the net profit over the trailing twelve months, with the owner's own salary, one off costs and anything personal added back, so that it measures what the business throws off for whoever runs it. Larger businesses are valued on EBITDA, which does not add back a manager's salary because a larger business has to pay one. The trailing twelve months matter because a buyer is paying for the year that just happened, and a seller who had a great year two years ago is selling last year.
What is added back is where the arguments are. The owner's salary, yes. A one time legal bill, yes. Advertising that was cut in the last quarter to flatter the profit, no, and a buyer's diligence finds it in the campaign history. Inventory is not in the figure at all: it is bought separately at cost, so a seller with six months of stock is paid for the stock and for the profit, and a seller with too much stock is paid for stock a buyer did not want.
The multiple, and why it fell
Brokers report that most Amazon FBA businesses sell in 2026 at between 2.5 and 4 times seller's discretionary earnings, with the strongest brands above that and the smallest or riskiest below. That is the brokers' report rather than a rule, and the range moves with the year. At the 2021 peak, when the aggregators were buying, the same businesses fetched 4 to 6 times; the aggregators consolidated or withdrew, buyers became more careful, and the multiple compressed to where it is.
The multiple is a price for risk. A buyer paying three times profit is betting the profit continues for three years, and every fact about the business that makes that more or less likely moves the figure. A business whose revenue is one product, on one marketplace, ranked on one term, with a supplier the buyer has never heard of, is a three year bet with a lot of ways to lose. The same profit from six products across Amazon and two other channels, with two suppliers and a brand people search for, is a safer bet and priced as one.
The six things that move a business up the range
One, age and consistency: three years of stable or growing profit, with the seasonality explained, beats one strong year. Two, concentration: no single product or search term carrying most of the sales, and, increasingly, sales beyond Amazon, because the multiple buyers pay for revenue that does not depend on one platform's rules is higher. Three, the brand: registered, with a store, with reviews that name it, with a share of search that is the brand's name, because a brand is a reason customers come back that does not need to be re-bought with advertising every month.
Four, the account: health rating in the green, no violations on the record, no notices in the last year, because a deactivation during the transfer is the one thing every buyer fears. The account health article is the work. Five, the supply chain: written agreements with suppliers, more than one supplier for the top products, and the trademark and Brand Registry roles transferable to the buyer. Six, the books: a profit and loss by month that ties to the Amazon settlements, the advertising and the FBA fees separated, and the unit economics per product, which is the same discipline as what it costs to sell on Amazon kept as a monthly habit rather than a one time exercise.
The year before the sale
The multiple is paid on the trailing twelve months, so the year before a sale is the year that is sold, and it is planned as one. The books are put in order first, because every later decision is read from them. Advertising is run for profit rather than growth, since a buyer counts profit and discounts growth bought with spend. Stock is brought to a level that covers the sale process without a stock out during diligence, which resets rank at the worst possible time, and without a mountain the buyer has to pay for. The account is kept spotless. New products are launched early in the year or not at all, because a launch in the last quarter is a cost in the figures and an unproven promise in the pitch.
The risks a buyer will price are the ones a seller can reduce beforehand: a second supplier sourced, a second channel opened even at small volume, a trademark registered, a review problem fixed. Each of those moves a business a step up the range, and the range is wide enough that a step is worth more than a year's profit. For the brands we run, this is the unit economics work done with an exit in mind, which is the same work done with the next year in mind: the profit that survives the sale is the profit that survives at all. The models an FBA business can be built on, and their different risks, are set out in the FBA versus dropshipping article.
Frequently asked questions
The questions that come up most often on this subject.
As a multiple of the profit a new owner would keep, measured for smaller businesses as seller's discretionary earnings over the trailing twelve months (net profit with the owner's salary and one off costs added back) and for larger ones as EBITDA. Inventory is bought separately at cost.
Brokers report 2.5 to 4 times seller's discretionary earnings for most, with strong brands above and small or risky businesses below. At the 2021 peak the same businesses fetched 4 to 6 times; the aggregators' retreat and more careful buyers compressed the range.
Three or more years of consistent profit, no single product or term carrying the sales, revenue beyond Amazon, a registered brand people search for, a clean account, written supplier agreements with a second supplier, and books that tie to the settlements by month.
No. Inventory is paid for separately at cost on top of the multiple. Too much stock is stock a buyer did not want to pay for, and a stock out during diligence resets rank at the worst time, so the level is planned for the sale.
A year before. The price is paid on the trailing twelve months, so that year is the one being sold: books in order, advertising run for profit, the account clean, stock sized for the process, and any launch done early or not at all.